
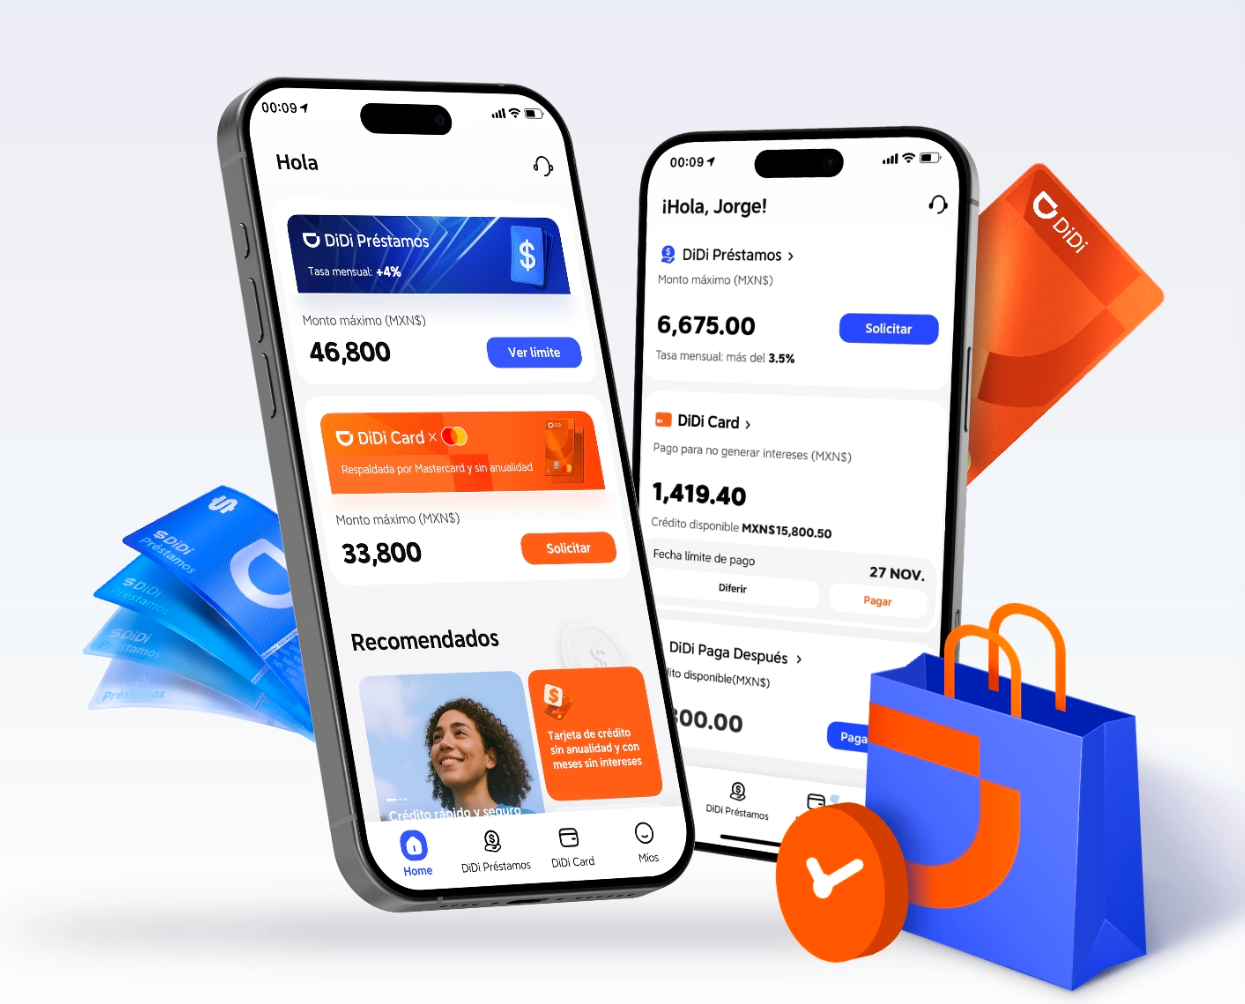
Why speed matters for the user
Waiting for your earned pay to land in your account is a real drag, especially if you run on tight cashflow—drivers, delivery partners, or freelancers feel this most. When a platform promises faster settlement, you expect it to mean near-instant access. That’s exactly the user thread that drives didi finanzas design: reduce latency between SPEI settlement and wallet availability so riders and drivers can keep moving without a gap. SPEI is Mexico’s instant payment rail run by Banco de México, and integrating with it intelligently is the backbone of any fast-pay UX.
How DiDi Finanzas actually processes a released pay
The app uses an API-first approach to talk to bank rails and internal ledgers. At a high level: a payroll release triggers a settlement request over SPEI, the payment clears, and the platform posts the funds to your in-app wallet. That chain involves tokenization, KYC checks, and reconciliation logic—each a tiny gate that can add seconds or minutes. With optimized routing and parallel reconciliation, the didi finanzas app trims those pauses and surfaces money faster to users.
Real test from the field — Mexico City run
I tried this with a small payout on a weekday afternoon in Mexico City to see what felt different. The SPEI settlement showed on the bank side within the expected window. What changed was the wallet sync: the app polled and reconciled quickly, and my in-app balance updated noticeably sooner than older platforms I used. The visible difference: about a few minutes saved on average—small per transaction, big over a month for daily earners. This was hands-on, not just theory, and it aligned with SPEI’s role as the instant rail.
Common mistakes people make with fast-pay services
People assume “instant” means zero work. That’s not true. Common missteps:
- Skipping KYC or outdated bank info, which stalls settlement.
- Ignoring cutoff windows—some banks batch processing at certain hours and that adds delay.
- Relying on a single payment route instead of services that can fall back between SPEI and internal ledger credits.
Alternatives to DiDi Finanzas are direct SPEI transfers from your bank or other fintech pay-later products. But those can trade convenience for predictable timing or charge different fees. The key is matching latency tolerance, settlement guarantees, and fees to your cashflow needs.
What to check before you trust a fast-pay solution
Here are pragmatic checks that matter for real users and operators:
- Settlement time: measure how long between release and wallet credit on average.
- Success rate: percentage of releases that post without manual reconciliation.
- Support and reconciliation: how quickly exceptions are resolved and funds returned or corrected.
These metrics map directly to user experience—lower latency plus high success equals fewer interruptions in daily life. —And if a platform hides fees inside processing language, that will show up in your effective payout.
Three golden rules to evaluate fast-pay services
When you compare providers, apply these evaluation metrics:
- Latency (end-to-end): look for median and tail times, not just the best-case.
- Reliability: track reconciliation rates and how often human intervention is needed.
- Transparent pricing: know per-transfer fees and any chargebacks or reversal costs.
These rules keep decisions practical and centered on what users actually feel in their wallets.
DiDi Finanzas fits into that picture by focusing on quick reconciliation, sensible fallbacks, and clear visibility into settlement—so your pay actually works like pay should. Final thought: trust the numbers, watch the latency, and choose the service that treats your time as currency.